Quantitative Aptitude
Dishonest Dealings
FMT-01
पडताळलेले उत्तर (Verified)
MPSC सराव प्रश्न:
एक अप्रामाणिक दुकानदार 30/किलो रुपयांना आंबा विकतो 20/किलो रुपयांना खरेदी करतो आणि तो 1 किलो ऐवजी 800 ग्रॅम देत आहे. दुकानदाराच्या वास्तविक नफ्याची टक्केवारी काय आहे?
A dishonest shopkeeper sells mangoes at Rs. 30/kg bought at Rs. 20/kg and he is giving 800 g instead of 1 kg. The shopkeeper's actual profit percentage is:
पर्याय (Options):
A
75%
B
37.5%
C
50%
D
अचूक उत्तर (Official Answer)
87.5%
सविस्तर स्पष्टीकरण (Detailed Explanation):
अचूक उत्तर: पर्याय (4)
दिलेले आहे:
आंब्याची खरेदी किंमत = 20 रुपये प्रति किलो
आंब्याची विक्री किंमत = 30 रुपये प्रति किलो
1000 - 800 = 200 ग्रॅमने फसवणूक
वापरलेले सूत्र:
नफा % = (नफा / खरेदी किंमत) × 100
नफा = (विक्री किंमत – खरेदी किंमत)
गणना:
1000 ग्रॅम साखरेची खरेदी किंमत = 20 रुपये
1 ग्रॅम साखरेची खरेदी किंमत = 20/1000
त्याने फक्त 800 ग्रॅम दिले आणि 200 ग्रॅम घेऊन ग्राहकाची फसवणूक केली
तर 800 ग्रॅम साखरेची खरेदी किंमत = (20 × 800)/1000
800 ग्रॅम साखरेची खरेदी किंमत = 16
साखरेची विक्री किंमत = 30
नफा = 30 - 16 = 14
नफा % = (नफा / खरेदी किंमत) × 100
⇒ (14/16) × 100
⇒ 87.5 %
∴दुकानदारांनी मिळवलेला नफा 87.5% आहे
Shortcut Trick
+-------+--------+--------+
| | ख. किं | वि.किं |
+-------+--------+--------+
| रुपये | 20 | 30 |
| रक्कम | 800 | 1000 |
+-------+--------+--------+
⇒ ख. किं : वि.किं = 20 × 800 : 30 × 1000
⇒ ख. किं : वि.किं = 16 : 30 ⇒ P = (30 - 16= 14)
नफा % = (14/16) × 100 = 87.5%
स्पष्टीकरण आकृती (Solution Visual Diagram):
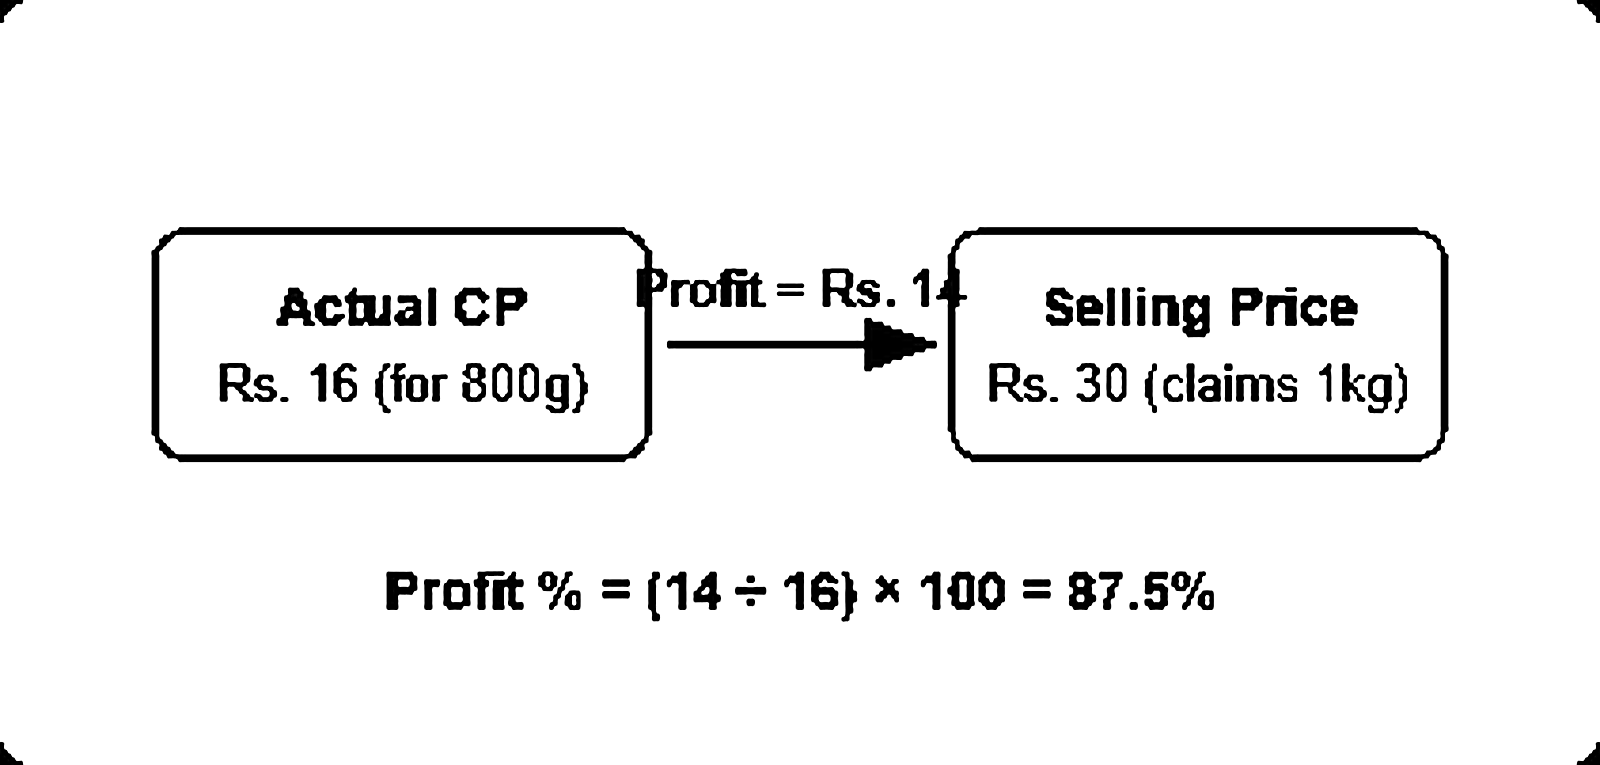

स्पष्टीकरणाची आकृती / संदर्भ तक्ता
Solution Diagram
परीक्षेतील संभाव्य चूक / Exam Trap:
परीक्षेतील संभाव्य चूक: विद्यार्थी अनेकदा पर्याय 1 ('75%') आणि पर्याय 4 ('87.5%') यामध्ये गोंधळात पडतात. प्रश्न नीट वाचून संकल्पनेतील सूक्ष्म भेद लक्षात घेणे आवश्यक आहे.
स्मृती क्लृप्ती / Memory Booster & Mnemonic:
+-------+--------+--------+ | | ख. किं | वि.किं |
पर्याय निर्मूलन पद्धत / Option Elimination Strategy:
🎯 पर्याय बाद पद्धत (Option Elimination Strategy): • पर्याय 1 ('75%'): हा पर्याय अयोग्य आहे. आयोगाच्या संदर्भानुसार अचूक उत्तर '87.5%' हे ठरते. • पर्याय 2 ('37.5%'): हा पर्याय अयोग्य आहे. आयोगाच्या संदर्भानुसार अचूक उत्तर '87.5%' हे ठरते. • पर्याय 3 ('50%'): हा पर्याय अयोग्य आहे. आयोगाच्या संदर्भानुसार अचूक उत्तर '87.5%' हे ठरते. • निष्कर्ष: त्यामुळे उर्वरित पर्याय बाद होऊन अचूक उत्तर पर्याय 4 ('87.5%') निश्चित होते.